
New Delhi: Want to become a crorepati by the time you retire at 60? Starting a Systematic Investment Plan (SIP) early and investing regularly could help you build a substantial retirement corpus. The amount you need to invest every month depends on your current age, investment horizon and expected returns.
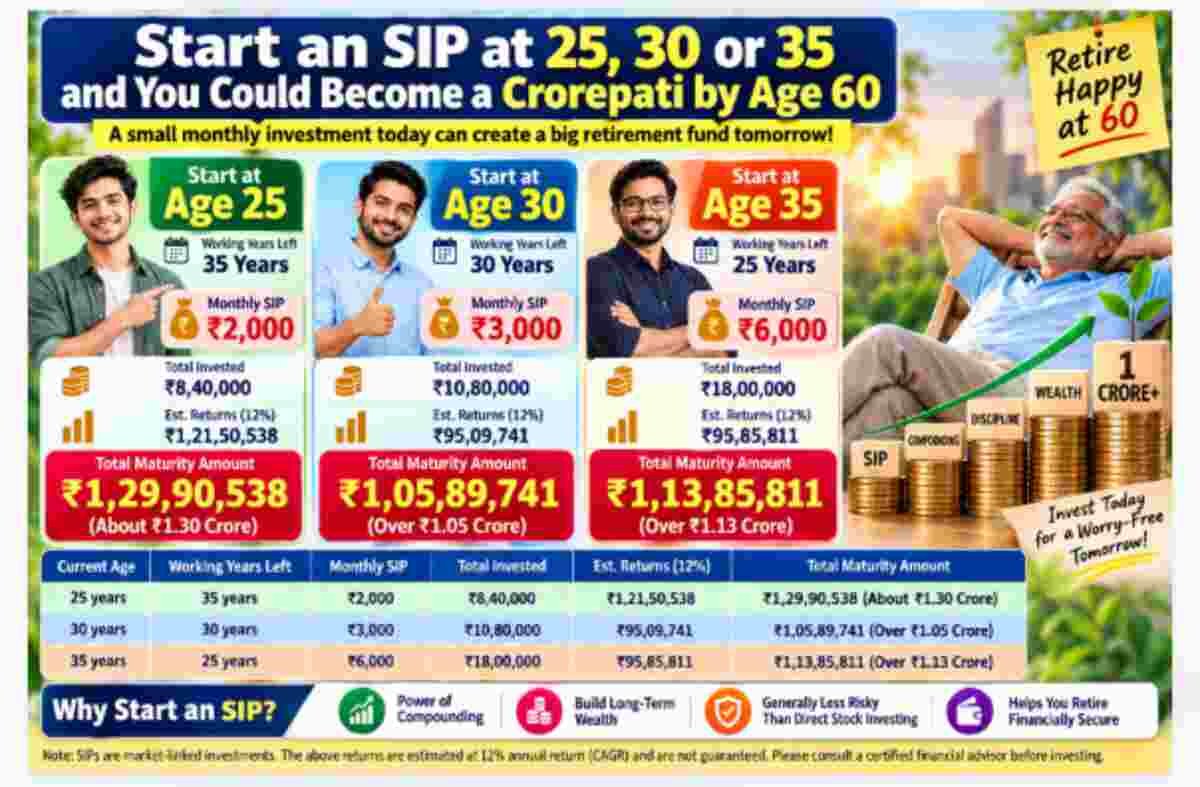
For example, assuming an illustrative annual return of 12%, a monthly SIP of ₹2,000 starting at age 25 could grow to approximately ₹1.30 crore over 35 years. Someone starting at 30 could target a similar milestone with a ₹3,000 monthly SIP over 30 years, while an investor beginning at 35 could aim to cross ₹1 crore by investing ₹6,000 every month for 25 years.
These figures are estimates, not guaranteed outcomes. Mutual fund investments are subject to market risks, and actual returns may vary.
Why Retirement Planning Should Start Early
Retirement planning is an essential part of long-term financial management. Once regular employment income stops, your savings and investments may become the primary sources of income for everyday expenses, healthcare and other financial needs.
Starting early gives your investments more time to grow. Even a relatively small monthly contribution can potentially accumulate into a substantial corpus when maintained over several decades.
If you have not started investing for retirement, begin by calculating how many years remain until your planned retirement age. You can then determine a suitable monthly SIP based on your income, expenses, financial goals and risk tolerance.
How Many Working Years Do You Have Left?
For this illustration, retirement is assumed to take place at age 60. Your remaining investment period can be calculated by subtracting your current age from 60.
- Age 25: 35 years remaining until retirement.
- Age 30: 30 years remaining until retirement.
- Age 35: 25 years remaining until retirement.
The longer your investment horizon, the more time your money has to benefit from compounding. However, the final corpus will also depend on investment performance and the amount contributed.
How Much SIP Is Needed to Build a ₹1 Crore Retirement Corpus?
1. Starting at Age 25: Invest ₹2,000 Per Month
Investors who begin at 25 have 35 years to prepare for retirement. Starting with a modest monthly contribution can help establish a regular investing habit while leaving room to increase contributions as income grows.
- Monthly SIP: ₹2,000
- Investment period: 35 years
- Total amount invested: ₹8.40 lakh
- Illustrative maturity value: Approximately ₹1.30 crore
Under the assumed return scenario, the investment could grow substantially beyond the amount contributed. This example highlights the potential benefit of starting early and staying invested over the long term.
2. Starting at Age 30: Invest ₹3,000 Per Month
At age 30, you still have three decades to build your retirement savings. A monthly SIP of ₹3,000 could potentially help you cross the ₹1 crore milestone by age 60.
- Monthly SIP: ₹3,000
- Investment period: 30 years
- Total amount invested: ₹10.80 lakh
- Illustrative maturity value: Approximately ₹1.06 crore
The example demonstrates how consistent contributions over a long period can help build wealth. Investors should remember that market fluctuations can cause the actual final value to differ from the projection.
3. Starting at Age 35: Invest ₹6,000 Per Month
Starting at 35 leaves 25 years until the assumed retirement age. With a shorter investment horizon, a higher monthly contribution may be needed to pursue the same financial goal.
- Monthly SIP: ₹6,000
- Investment period: 25 years
- Total amount invested: ₹18 lakh
- Illustrative maturity value: Approximately ₹1.14 crore
Although the monthly investment is higher, a disciplined approach over 25 years could potentially help build a retirement fund exceeding ₹1 crore, provided the assumed return is achieved.
Age-Wise SIP Calculation: Investment, Returns and Maturity Value
| Current age | Years invested | Monthly SIP | Total investment | Estimated returns | Estimated corpus |
|---|---|---|---|---|---|
| 25 years | 35 | ₹2,000 | ₹8.40 lakh | ₹1.22 crore | ₹1.30 crore |
| 30 years | 30 | ₹3,000 | ₹10.80 lakh | ₹95.10 lakh | ₹1.06 crore |
| 35 years | 25 | ₹6,000 | ₹18 lakh | ₹95.86 lakh | ₹1.14 crore |
Note: These are illustrative projections based on an assumed 12% annual return, with monthly SIP contributions made at the end of each month. Actual returns are not guaranteed. Figures are rounded for readability.
What Is an SIP and Where Is Your Money Invested?
A Systematic Investment Plan is a method of investing a fixed amount at regular intervals in a mutual fund. Depending on the selected fund, the money may be invested in equities, bonds or other permitted financial instruments.
SIPs offer several potential benefits for long-term investors:
Regular investing: Monthly contributions help develop financial discipline and reduce the need to invest a large lump sum at once.
Power of compounding: Over time, investment earnings can generate additional earnings, helping the corpus grow.
Flexible contributions: Investors can select a contribution that fits their budget and may increase it as their income rises.
Long-term wealth creation: Regular investing over an extended period can help investors work towards goals such as retirement, subject to market performance.
However, an SIP is not a separate investment product that guarantees returns. The risk depends on the underlying mutual fund. Equity funds can experience significant market fluctuations, while debt funds carry their own risks, including interest-rate and credit risks.
A 12% annual return is an assumption used for this calculation, not a guaranteed or universal average. Mutual funds do not necessarily outperform government-backed savings schemes.
Important Things to Consider Before Starting a Retirement SIP
Before investing, keep these factors in mind:
- Set a realistic goal: Estimate your retirement expenses and account for inflation, healthcare costs and your expected lifestyle.
- Choose an affordable contribution: Your SIP should fit comfortably within your monthly budget after essential expenses and debt obligations.
- Understand your risk tolerance: Select mutual funds based on your investment horizon, financial objectives and ability to withstand losses.
- Review your investments periodically: Check whether your contributions and retirement target remain appropriate as your circumstances change.
- Consider increasing your SIP: Raising your monthly investment as your salary grows may help you build a larger corpus.
- Maintain emergency savings: Keep sufficient funds accessible for unexpected expenses rather than relying entirely on long-term investments.
Conclusion: Start Early and Plan for a Financially Secure Retirement
Building a retirement corpus of ₹1 crore or more by age 60 may be achievable under certain investment assumptions, but it is not guaranteed. The examples show how different monthly SIP amounts and investment periods can influence the potential outcome.
Starting at 25 gives your investments more time to compound, while beginning at 30 or 35 may require higher monthly contributions. Your actual retirement target should also account for inflation, because ₹1 crore in the future will not have the same purchasing power as ₹1 crore today.
The most important steps are to start when you can, invest consistently, understand the risks and review your financial plan regularly. If you are unsure which mutual funds suit your goals, consider consulting a SEBI-registered investment adviser before making investment decisions.

