
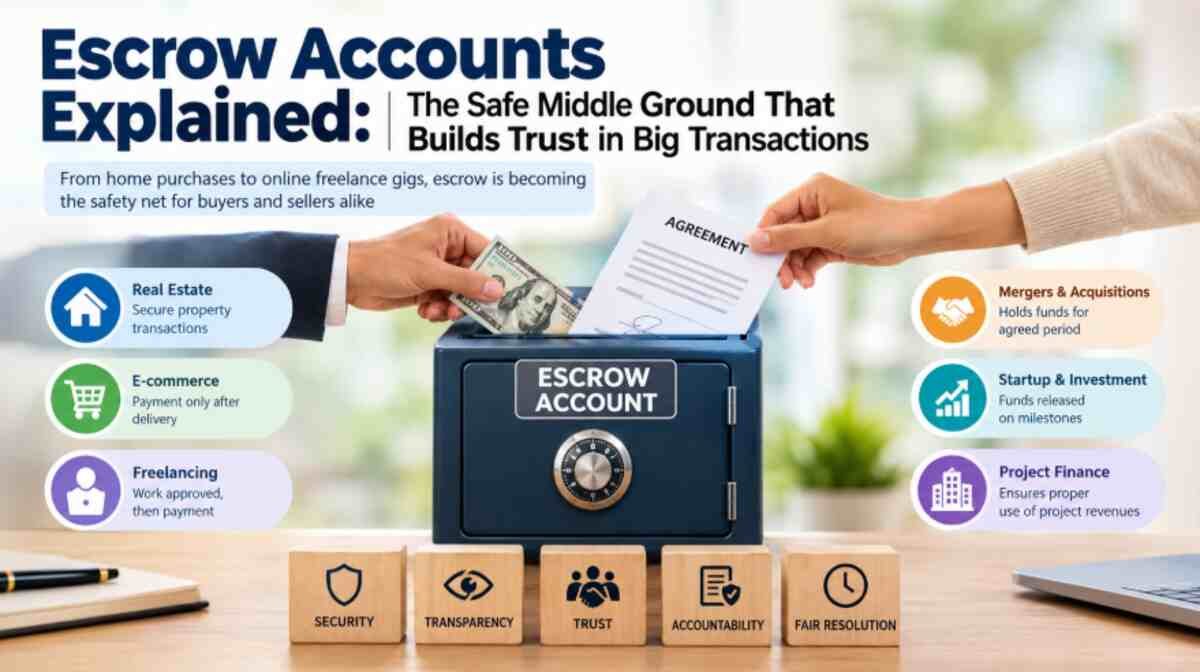
From home purchases to online freelance gigs, escrow is becoming the safety net for buyers and sellers alike
When a large sum of money changes hands, one question hangs over every deal: what if the other side doesn’t keep their promise? A buyer worries about paying and getting nothing in return. A seller worries about delivering and never being paid. Escrow accounts exist to solve exactly this problem, and their use is growing quickly across real estate, e-commerce, freelancing and corporate deals.
What Is an Escrow Account?
An escrow account is a holding account managed by a neutral third party, such as a bank, a financial institution or a licensed escrow agent. The buyer deposits the money into this account, and the agent releases it to the seller only when the agreed conditions are met.
Think of it as a trusted locker. The money is neither with the buyer nor the seller. It sits with an impartial party until both sides have done what they promised.
How Does Escrow Work?
The process usually follows a few clear steps.
1. Agreement: Buyer and seller put the terms of the deal in writing, including the amount, timelines, delivery or completion conditions, and how disputes will be resolved.
2. Choosing an agent: Both parties agree on a trustworthy bank or licensed escrow provider.
3. Deposit: The buyer transfers the agreed amount into the escrow account, and the agent confirms to the seller that the funds are secured.
4. Fulfilment: The seller delivers the goods, transfers the documents or completes the work as promised.
5. Verification: The agent, or the buyer through an approval step, confirms that the terms of the agreement have been met.
6. Release: Once verified, the funds go to the seller. If the conditions are not met, the money can be returned to the buyer as the agreement specifies.
Where Is Escrow Used?
Real estate: Property transactions are the classic use case. Buyers often place a deposit or part of the payment in escrow, which is released after title checks, documentation and registration are complete.
In India, escrow-style protection is built into the law for new housing projects. Under the Real Estate (Regulation and Development) Act, commonly called RERA, developers must deposit a major portion of the money collected from homebuyers, generally 70 percent, into a separate designated bank account. That money can be used only for the construction and land cost of that specific project. The aim is to prevent funds from one project being diverted to another, a problem that left many homebuyers stranded in the past. Exact rules can vary by state, so buyers should check their state RERA authority.
E-commerce and freelancing: Many online marketplaces hold the buyer’s payment until the product arrives or the work is approved. For freelancers, this offers reassurance that the client has already committed the money. For clients, it ensures payment depends on actual delivery.
Mergers and acquisitions: In company takeovers, a portion of the purchase price is often held in escrow for a set period. If hidden liabilities or problems surface after the deal closes, the buyer can recover losses from that fund.
Startup and investment deals: Investors sometimes keep funds in escrow until certain milestones or regulatory approvals are reached.
Project finance: In large infrastructure projects, lenders often require an escrow account into which project revenues are paid. The money is then used in a pre-agreed order, such as loan repayments first and other expenses afterwards.
Key Benefits of Escrow
Protection against fraud: Because the funds sit with a neutral party, the risk of a seller disappearing with the money, or a buyer refusing to pay, drops sharply.
Transparency: Every condition and step is documented, which provides a clear record if a disagreement arises.
Trust on both sides: Buyers know their money is not released until they receive what was promised. Sellers know the funds exist and are secured before they start work or hand over goods.
Structured dispute resolution: Well-drafted escrow agreements spell out what happens if the parties disagree, whether through arbitration, mediation or the courts.
Accountability: Defined deadlines and conditions push both parties to take their commitments seriously.
Drawbacks and Risks to Keep in Mind
Escrow is a strong safeguard, but it is not flawless.
Fees: Escrow agents charge for their services, usually a percentage of the transaction value or a flat fee. On small deals, this cost can feel heavy.
Delays: Verification and documentation take time, so the seller does not receive payment instantly.
Fake escrow scams: Fraudsters sometimes create convincing but fake escrow websites to trick victims into sending money. Always use a registered bank, a regulated financial institution or a well-established, verified platform. Never pay through a link sent by a stranger.
Poorly drafted agreements: If conditions are vague or incomplete, even an honest escrow agent may struggle to decide when funds should be released, which can lead to prolonged disputes.
What to Check Before Opening an Escrow Account
- Verify the agent’s credentials. Confirm they are licensed or regulated, and look at their track record and reviews.
- Read the agreement closely. Release conditions, deadlines, penalties and refund rules should all be stated clearly.
- Clarify the fees upfront. Know how much will be charged and who will pay it, the buyer, the seller or both.
- Use only official payment channels. Avoid personal accounts, unknown UPI IDs or payment links received over messaging apps.
- Take professional advice. For high-value deals, especially in property or business transactions, have a lawyer or chartered accountant review the documents.
The Future of Escrow
As digital payments and online marketplaces expand, so does demand for escrow. A growing number of fintech companies now offer technology-driven escrow services, allowing deposits, verification and release of funds to happen online and much faster than before.
In some markets, blockchain-based smart contracts are also being used as automated escrow, releasing funds the moment programmed conditions are satisfied. The legal and regulatory framework around such tools is still evolving, so users should rely on guidance from the relevant authorities and exercise caution.
The Bottom Line
An escrow account is not a magic solution, but it adds a strong layer of trust to transactions where a lot is at stake. Whether you are buying your first home, hiring a freelancer or closing a business deal, escrow ensures that money moves only when promises are kept.
The key is to choose a reliable agent, write a clear agreement and stay alert at every step. In financial dealings, trust matters, but trust backed by protection matters even more.
Disclaimer: This article is for general information only and does not constitute legal or financial advice. Consult a qualified lawyer or financial advisor before making major financial decisions.

